Institutional Insights: JPMorgan Trading The FOMC 16/9/26
EQUITY & MACRO STRATEGY BRIEFING: FOMC COUNTDOWN & SCENARIO ANALYSIS
Source Data: JPM Market Intel & Jay Barry (Head of US Rates Strategy)
THE TAKE: MARKET AT FED CROSSROADS AS BOND VOLATILITY DRIVES THE TAPE
With a 25 bps rate hike (~90% priced in for Wednesday) and a cumulative 76 bps of tightening discounted through 2027 Q1, client focus has shifted squarely to Chair Kevin Warsh's communication strategy, the ultimate terminal rate, and whether the Fed will unwind the late-2025 "insurance cuts."
JPMorgan Market Intel maintains a Tactically Cautious / Neutral posture into the FOMC decision. Underlying macro (above-trend GDP) and micro fundamentals (>20% EPS growth expected for 26Q3/26Q4) remain robust, but a 10-Year Treasury yield testing cycle highs (4.99%) and elevated rate volatility act as near-term equity friction. Historically, equities take up to 8 weeks to digest new 10Y cycle highs, and a 2-standard-deviation move in yields (~50–55 bps) typically triggers negative monthly equity returns.
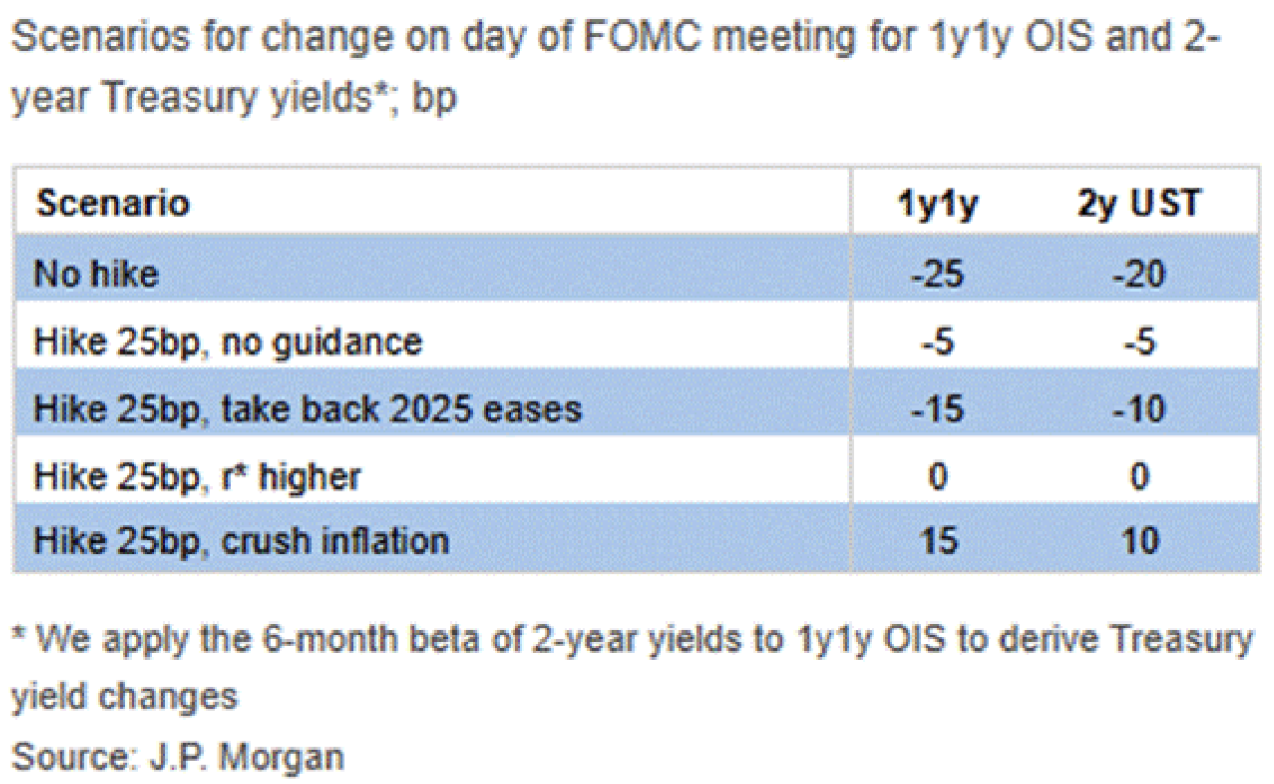
FOMC SCENARIO ANALYSIS
Scenario & Fed Decision | Rates & Macro Reaction | Projected SPX Move | Desk Take & Factor Impact |
|---|---|---|---|
1. NO HIKE (Surprise Hold) | Inflation expectations spike; 10s/30s curve steepens sharply. | SPX -1.25% to -1.75% | Negative: Severe loss of inflation credibility; rate volatility spikes. |
2. 25BP HIKE / NO GUIDANCE | Yield curve twists steeper; back-end moves contained. | SPX +0.25% to +0.75% | Consensus Base Case: Equities rally with a Large-Cap / Size bias. |
3. 25BP HIKE / REMOVE 2025 EASES | Market prices 75 bps total cycle; Oct/Dec vs. Dec/Mar timing. | SPX +0.50% to +1.00% | Bullish Clear-out: Rapid front-loading removes rate ambiguity through 2027. |
4. 25BP / HIGHER R-STAR (R∗) | Implies rates are 100–150 bps below neutral; 50 bps on table. | SPX -0.25% to -1.00% | Hawkish Shock: Heightened bond vol pressures equity multiples. |
5. 25BP / CRUSH INFLATION | Terminal rate signaled materially higher; 2022/23 rerun. | SPX -1.00% to -2.00% | Bear Tail Risk: Ends bull market narrative via valuation contraction. |
MARKET INTEL TACTICAL POSITIONING & MONETIZATION MENU
AI & Tech Dip-Buying: View the recent Software vs. Semis dislocation and AI hardware pullback as a tactical buying opportunity. Structural AI demand remains intact without evidence of revenue deterioration or margin compression. Preferred expressions: Semis, AI Infrastructure, and Mag7.
Yield Curve & Cyclical Rotations: A steeper yield curve post-FOMC directly supports Cyclicals and Large-Cap Banks. If long-end yields pull back, SMid-caps (Russell 2000) offer tactical outperformance potential.
Asymmetric Reopening Basket: If yields drop materially, beaten-down "2021 Reopening Plays"—Airlines, Autos, Footwear/Sportswear, Homebuilders, and Restaurants—present high-upside risk/reward as current positioning sits at single-digit percentiles.
Factors & Regional Allocations: Favor Momentum and Quality Growth factors; prefer LatAm equities for non-AI Emerging Market exposure.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!